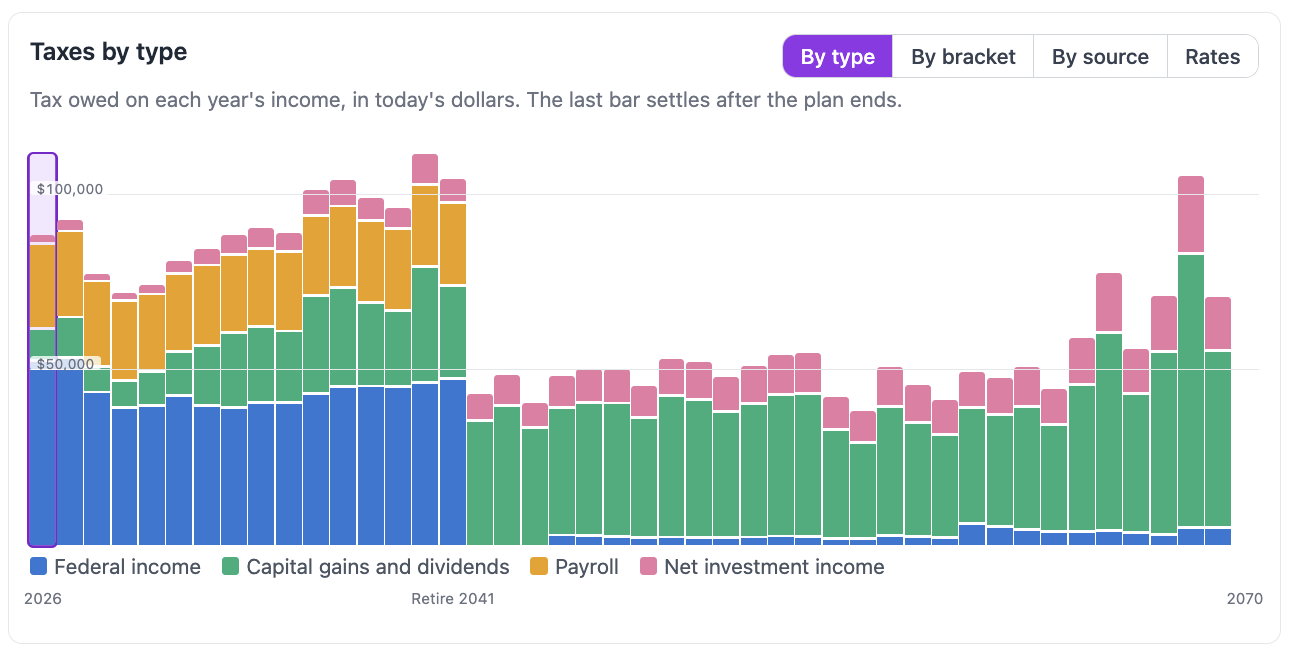
Taxes by type
Federal, state, capital gains and payroll, year by year. A one-off, like selling a rental, stands out as its own spike.
FIREproof enables you to model, plan, and visualize your retirement… and all that happens along the way.
A retirement planning tool from the creator of cFIREsim.com, a mainstay in the retirement calculator world and FIRE community.
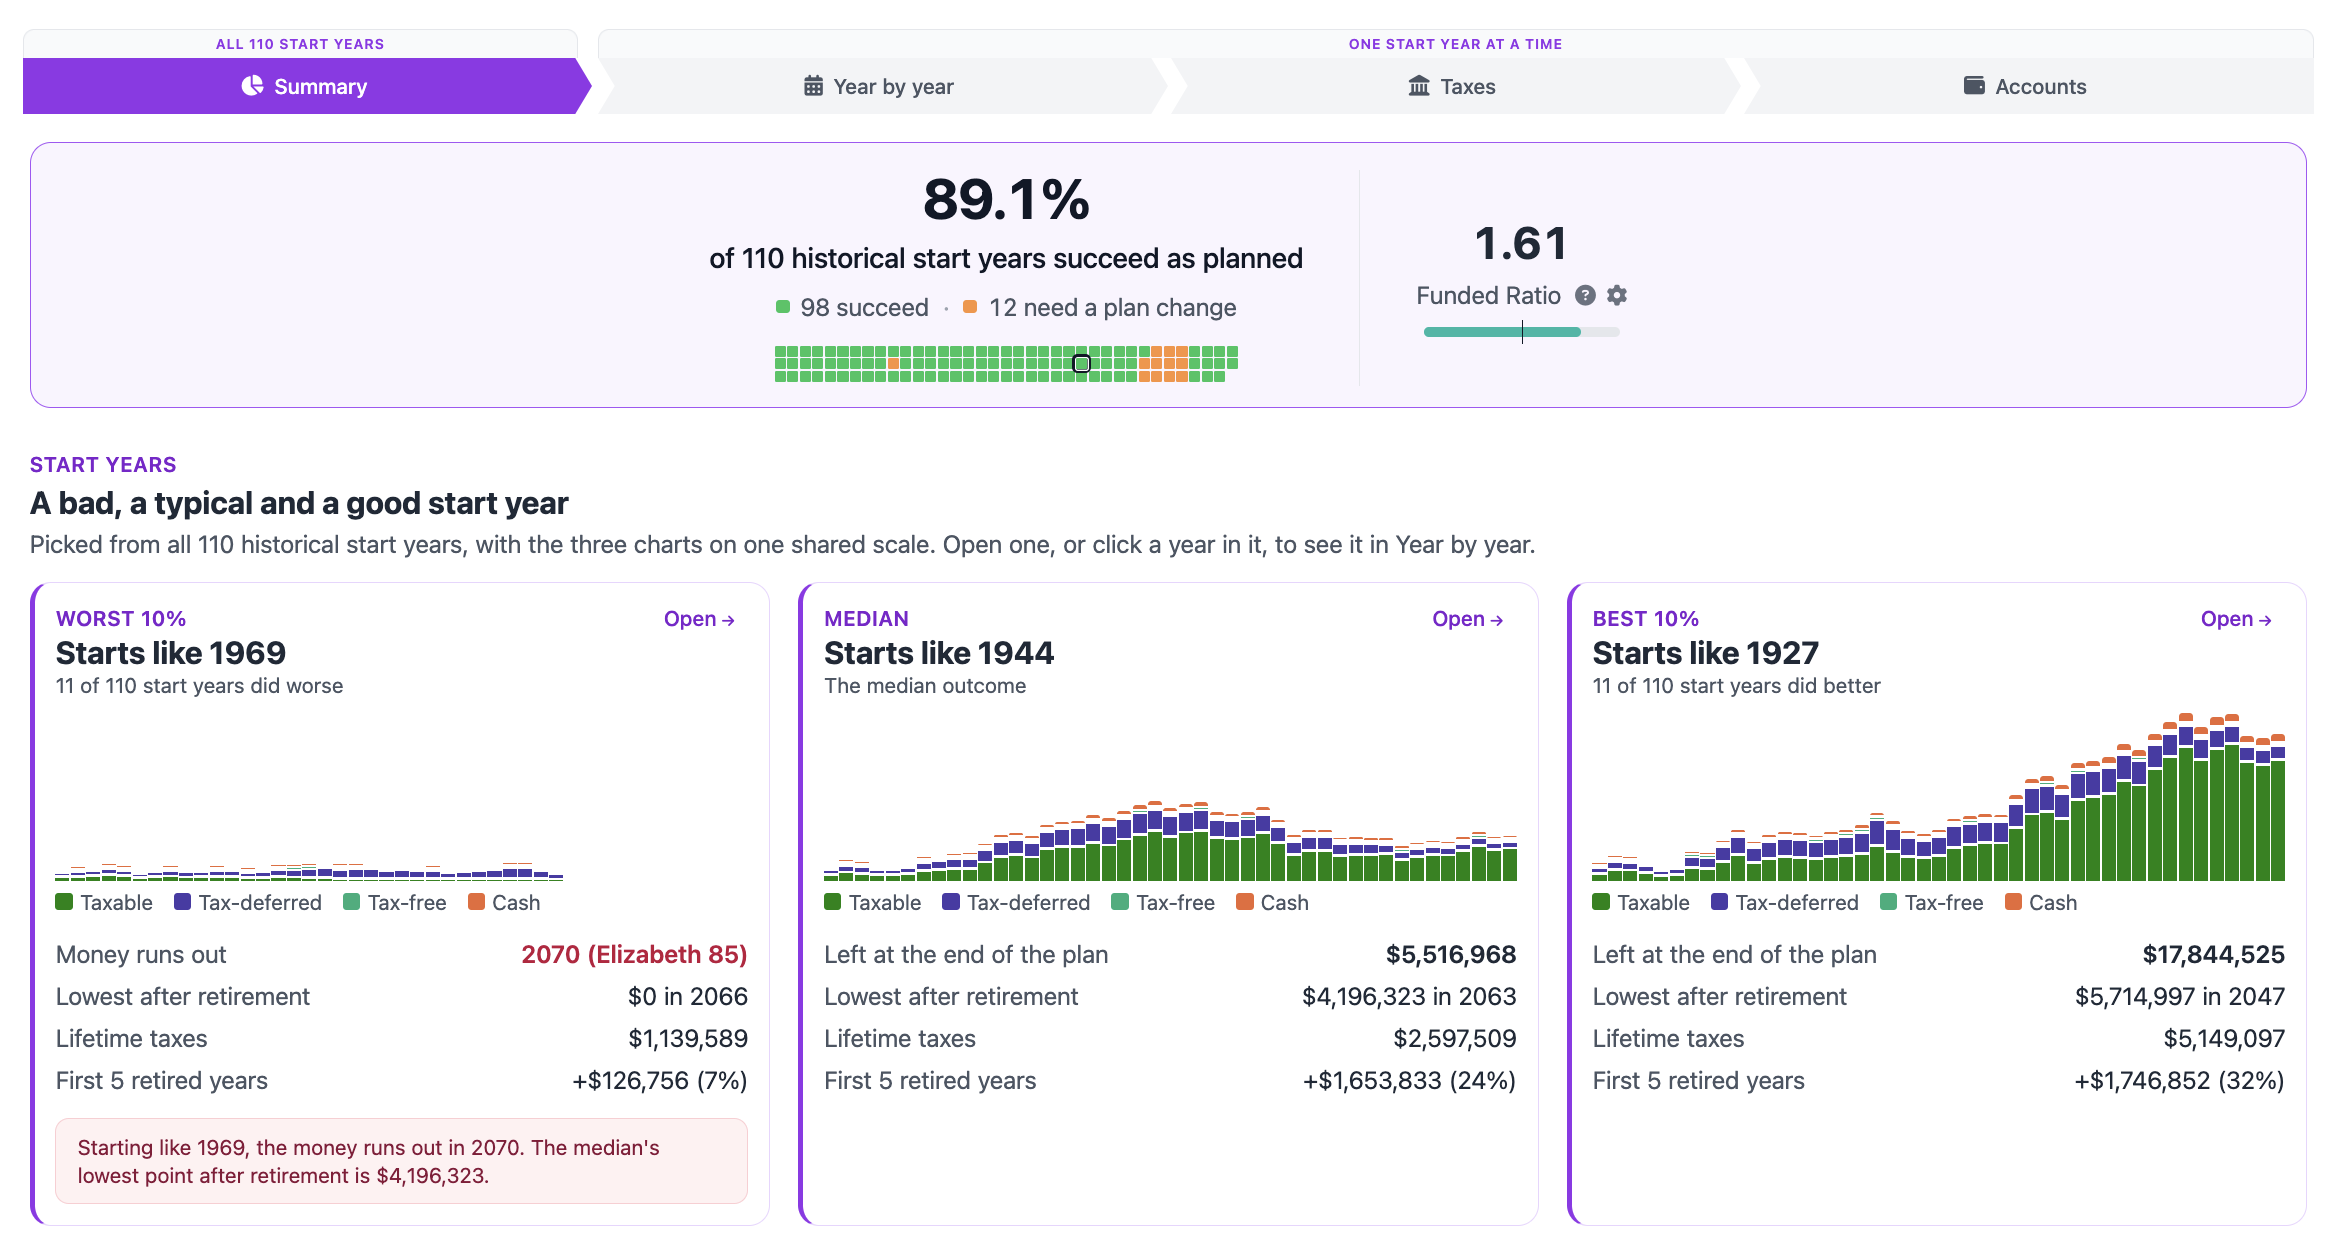
The verdict in plain words. How many historical start years your plan survives.
Every square is a real year. One per retirement start year since 1871. Orange ones needed a plan change.
Outcomes, not odds. A bad, a typical, and a good history, drawn on the same scale.
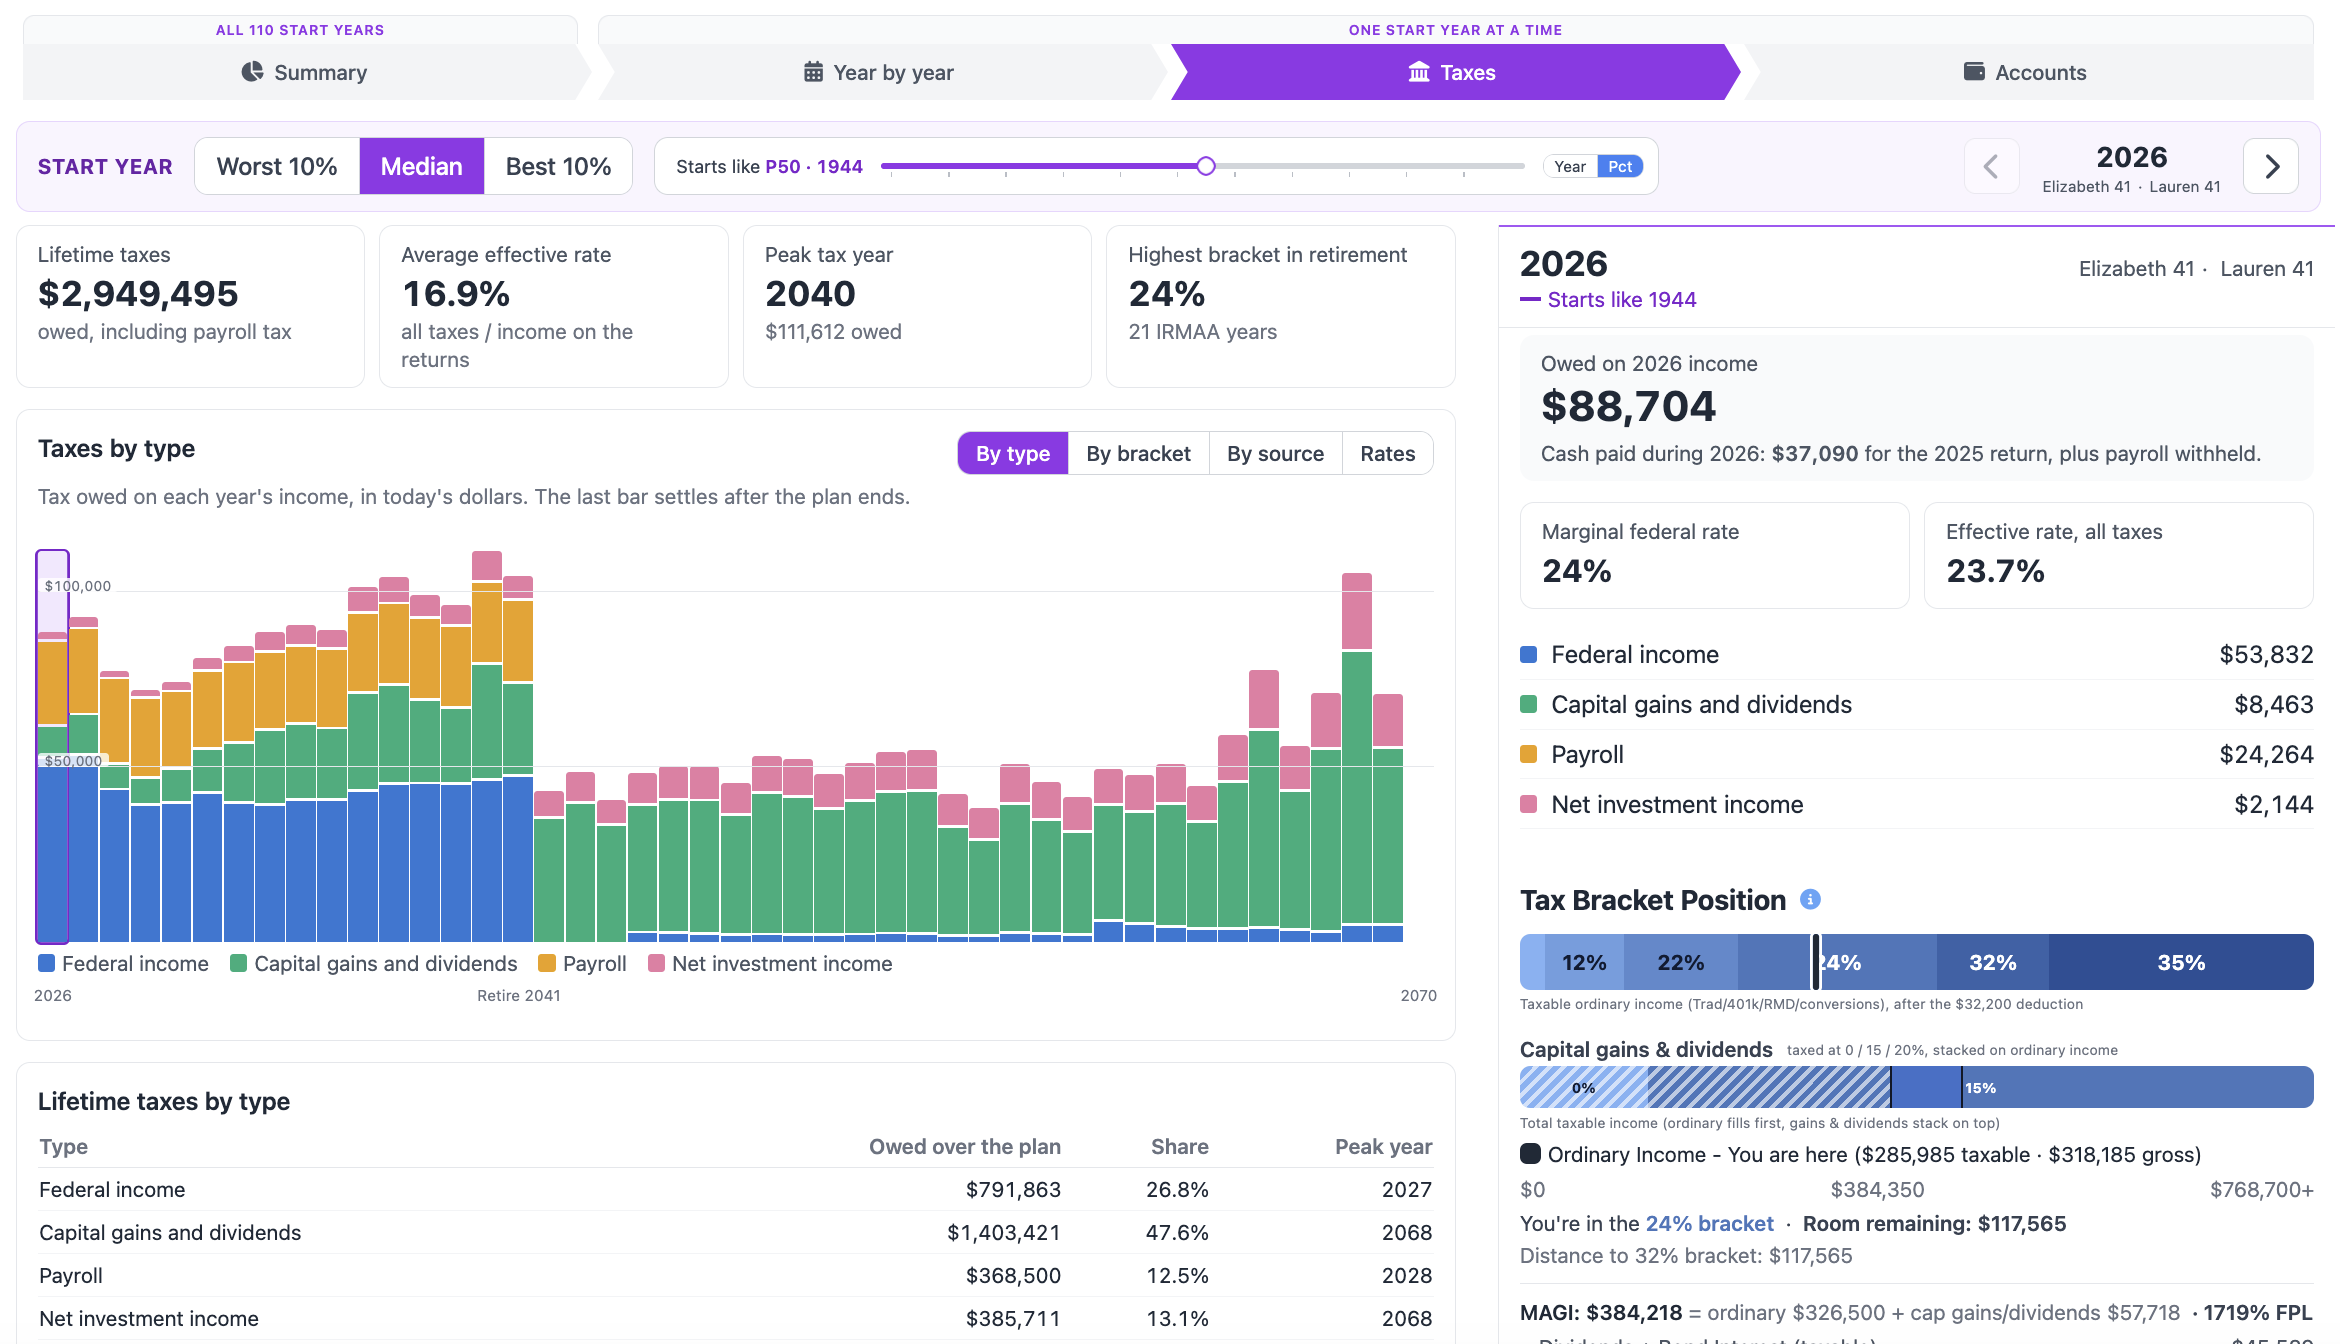
Every year of every history settles like a real tax return: income tax, capital gains with cost basis, payroll tax, RMDs, and 72(t) SEPP. Now you can read the return.
Federal, state, capital gains, and payroll, summed over the whole plan and split by type, with the peak year named.
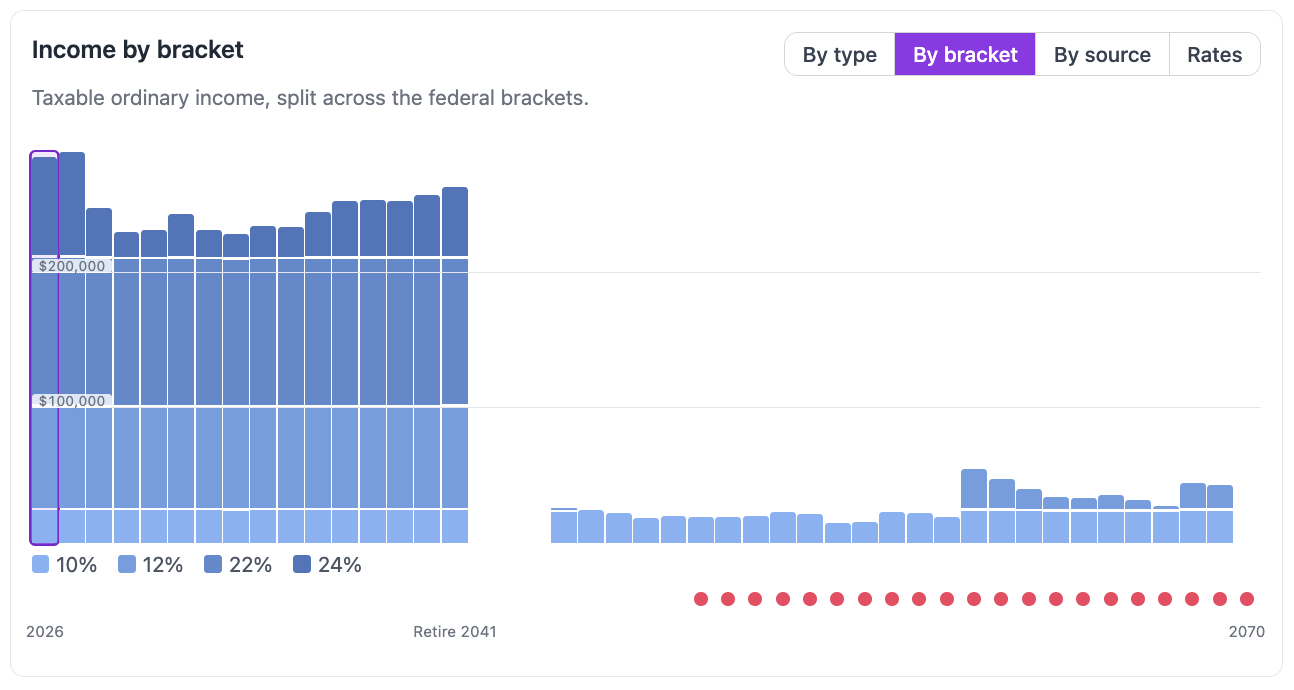
See how each year's income fills 10%, 12%, and 22%, with your bracket-fill target drawn right on the chart.
RMDs, Medicare IRMAA surcharges, and the years you spill past your target, called out before they surprise you.
ONE PLAN, FOUR VIEWS
Switch views on the Taxes tab. Click any year to see its return beside the chart.
Federal, state, capital gains and payroll, year by year. A one-off, like selling a rental, stands out as its own spike.
How full each bracket is every year, with your bracket-fill target drawn as a line, so the years that spill past it are easy to spot.
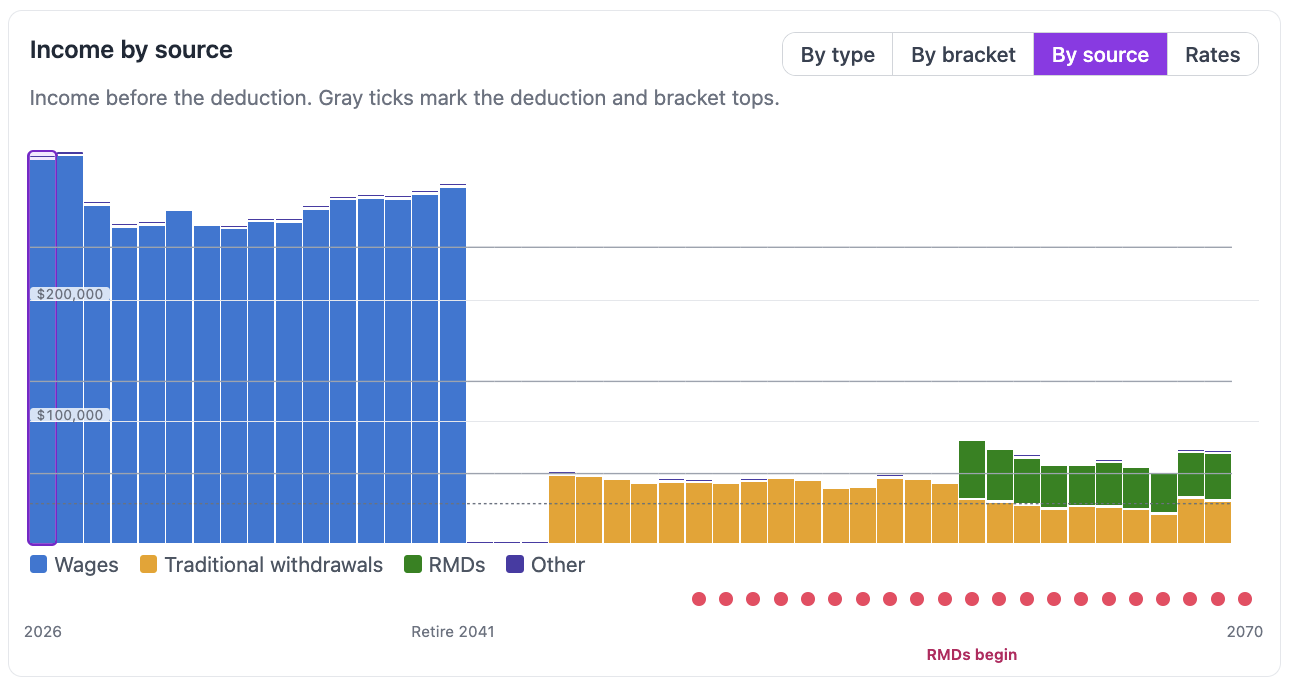
What fills each return: wages, then withdrawals and Roth conversions, then Social Security and RMDs, measured against your deduction.
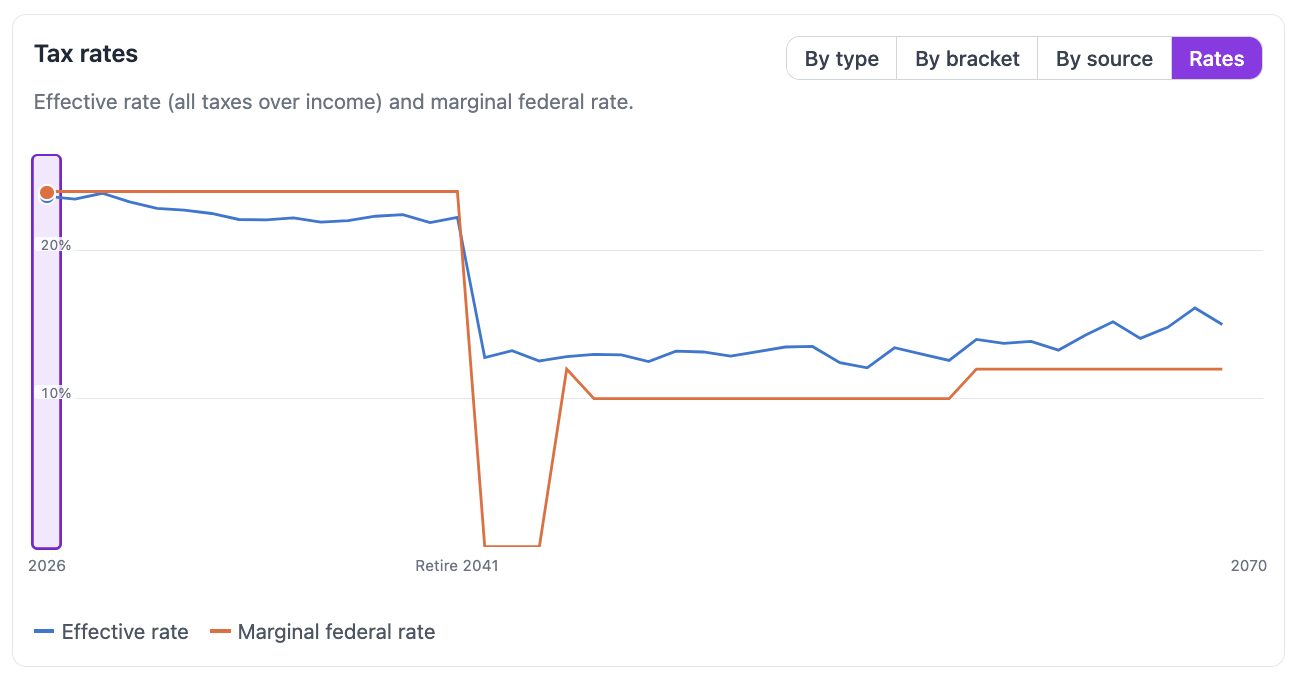
Your effective rate against your marginal rate, year by year: what you pay on average, and what the next dollar costs.
From real estate and ACA optimization to Roth conversions and the Bucket Strategy - explore everything FIREproof can model.
Draw down your portfolio with Guyton-Klinger, VPW, CAPE, or Hebeler autopilot, all backtested against 150 years of market history. See every strategy.
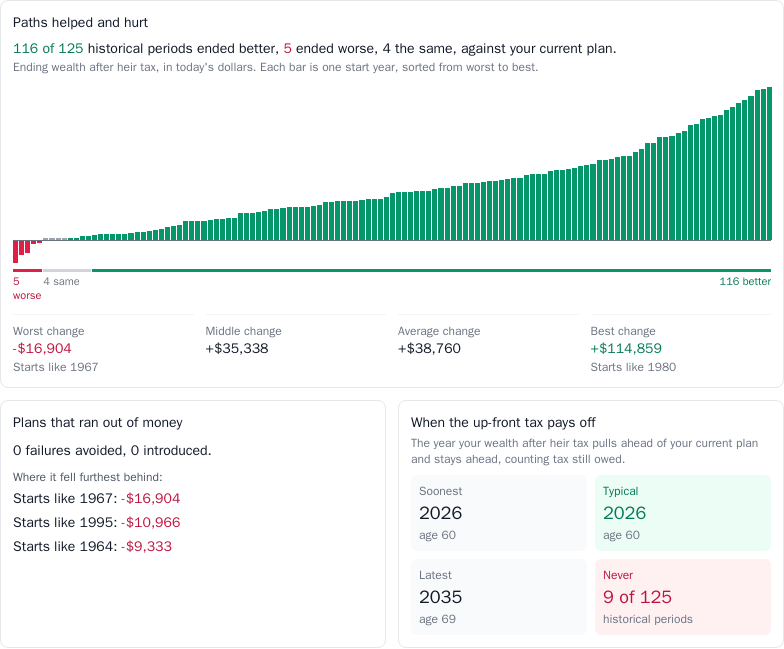
Compare Roth conversion and 72(t) strategies the way they would actually have played out. Not one average-return projection: every strategy in the results runs your whole plan through every historical start year, and How it holds up draws each one as a bar, worst to best, showing how much better or worse it ended than your current plan. Averages hide the losers. This shows you every one.
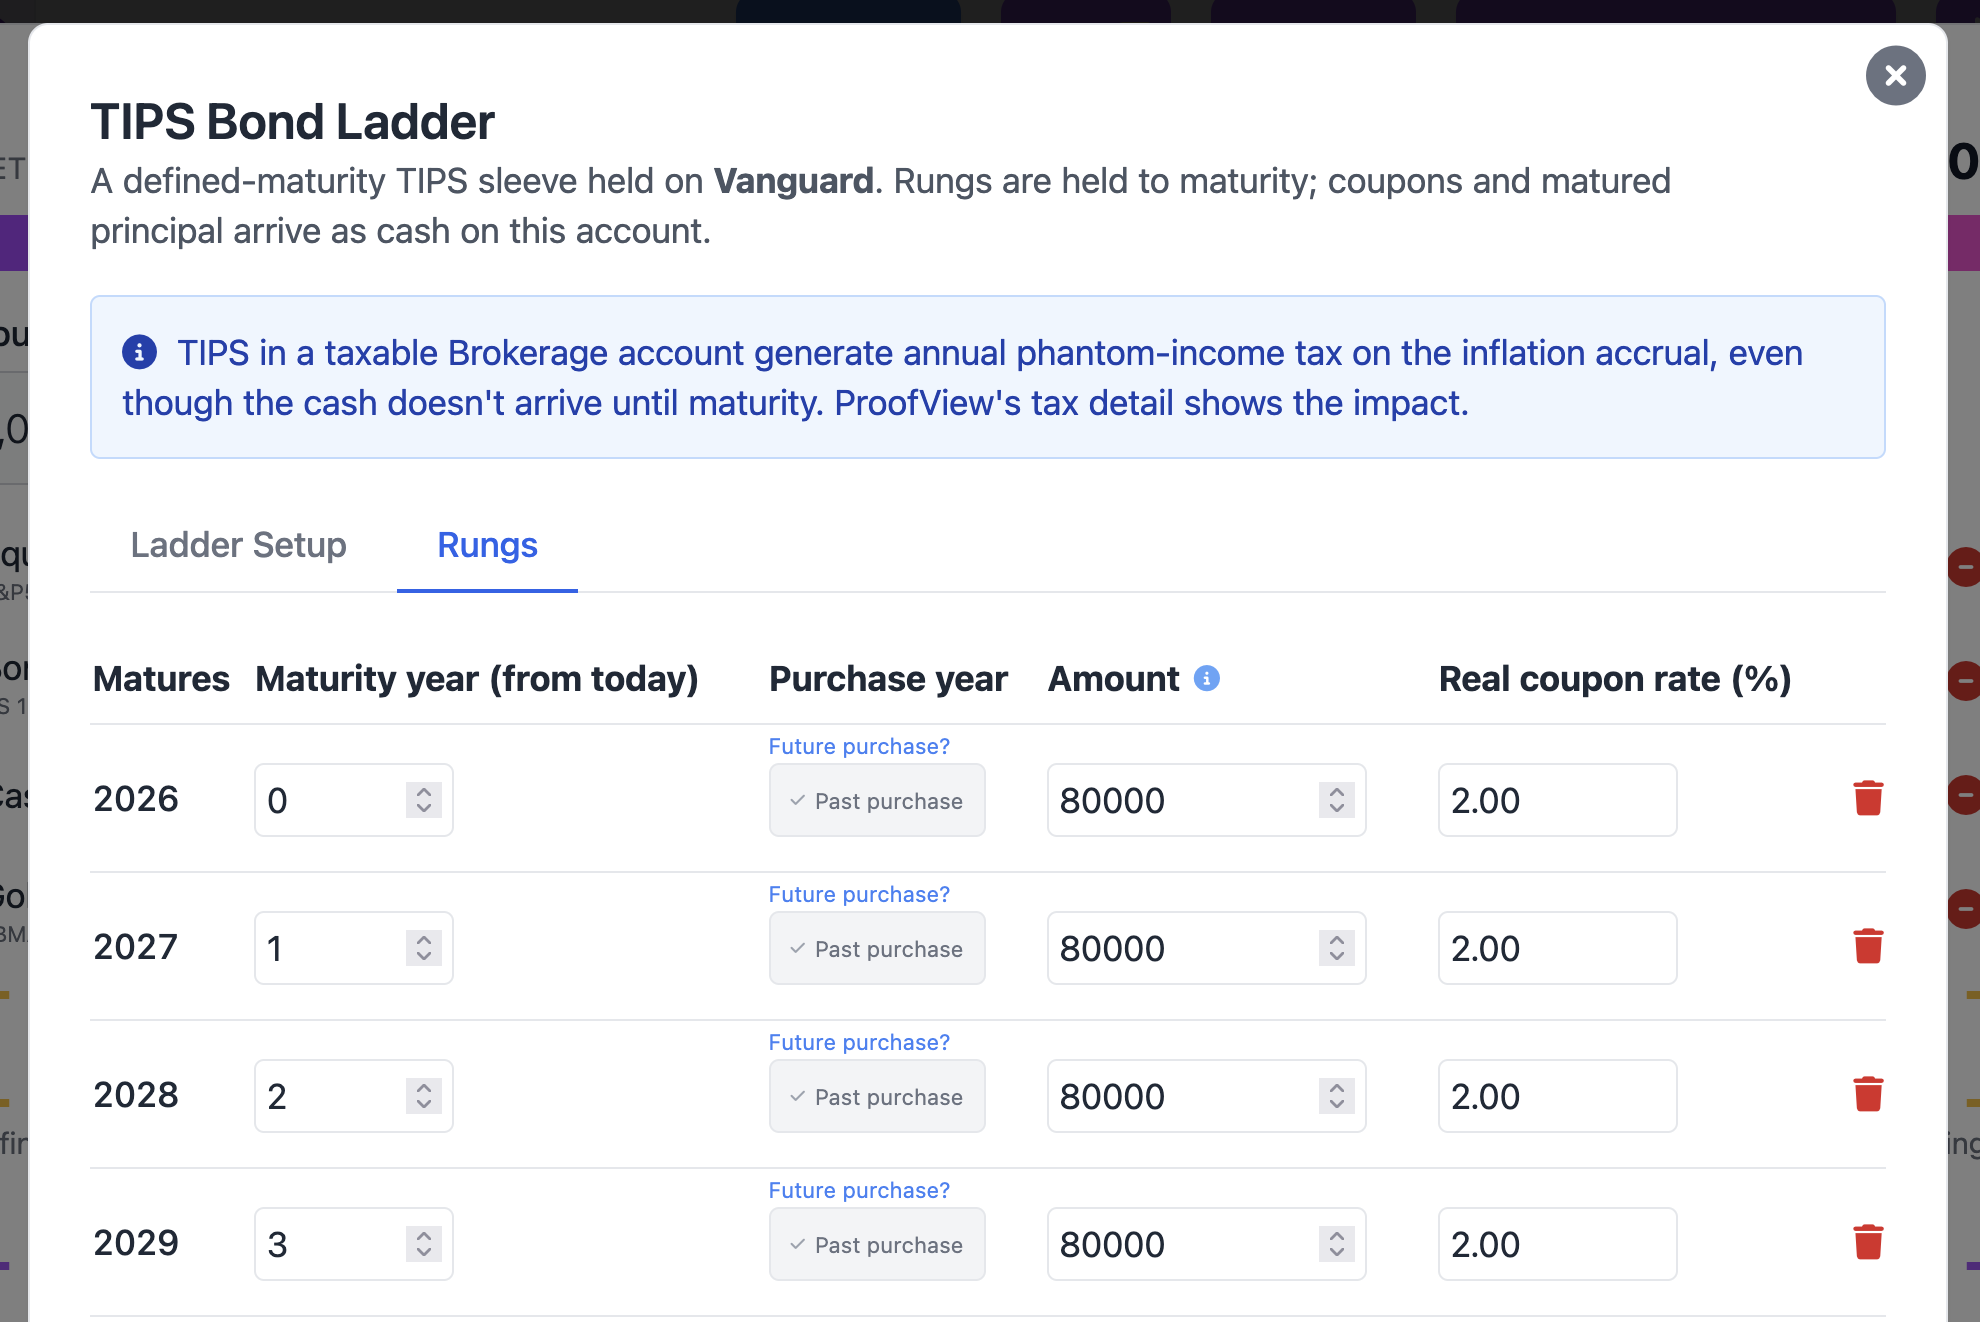
Each rung pays a guaranteed, inflation-adjusted amount in a specific year, so you fund the first part of retirement from maturing bonds instead of selling stocks into a downturn. Protect yourself from sequence-of-returns risk, then let your equities ride.
Auto-lookup marketplace premiums by ZIP. Project your subsidy each year and optimize withdrawals to maximize the Premium Tax Credit. Auto-ends at Medicare age.

Manual or optimizer-mode Roth conversions. See bracket room, model the 5-year rule, and compare lifetime tax with and without conversions.

A market-aware three-bucket withdrawal strategy. Pauses growth-bucket sales during bear markets, refills aggressively in good ones.

Model homes you own and homes you'll buy. Track mortgages year-by-year, project appreciation, plan a future purchase, run rental cash flow with depreciation, and even model a 1031 exchange.

Choose how each year's spending is sourced, then see the reasoning explained year by year.
Explore the full simulator with a pre-built scenario. Same engine, same charts. Tweak retirement age, spending, and allocation in real time.
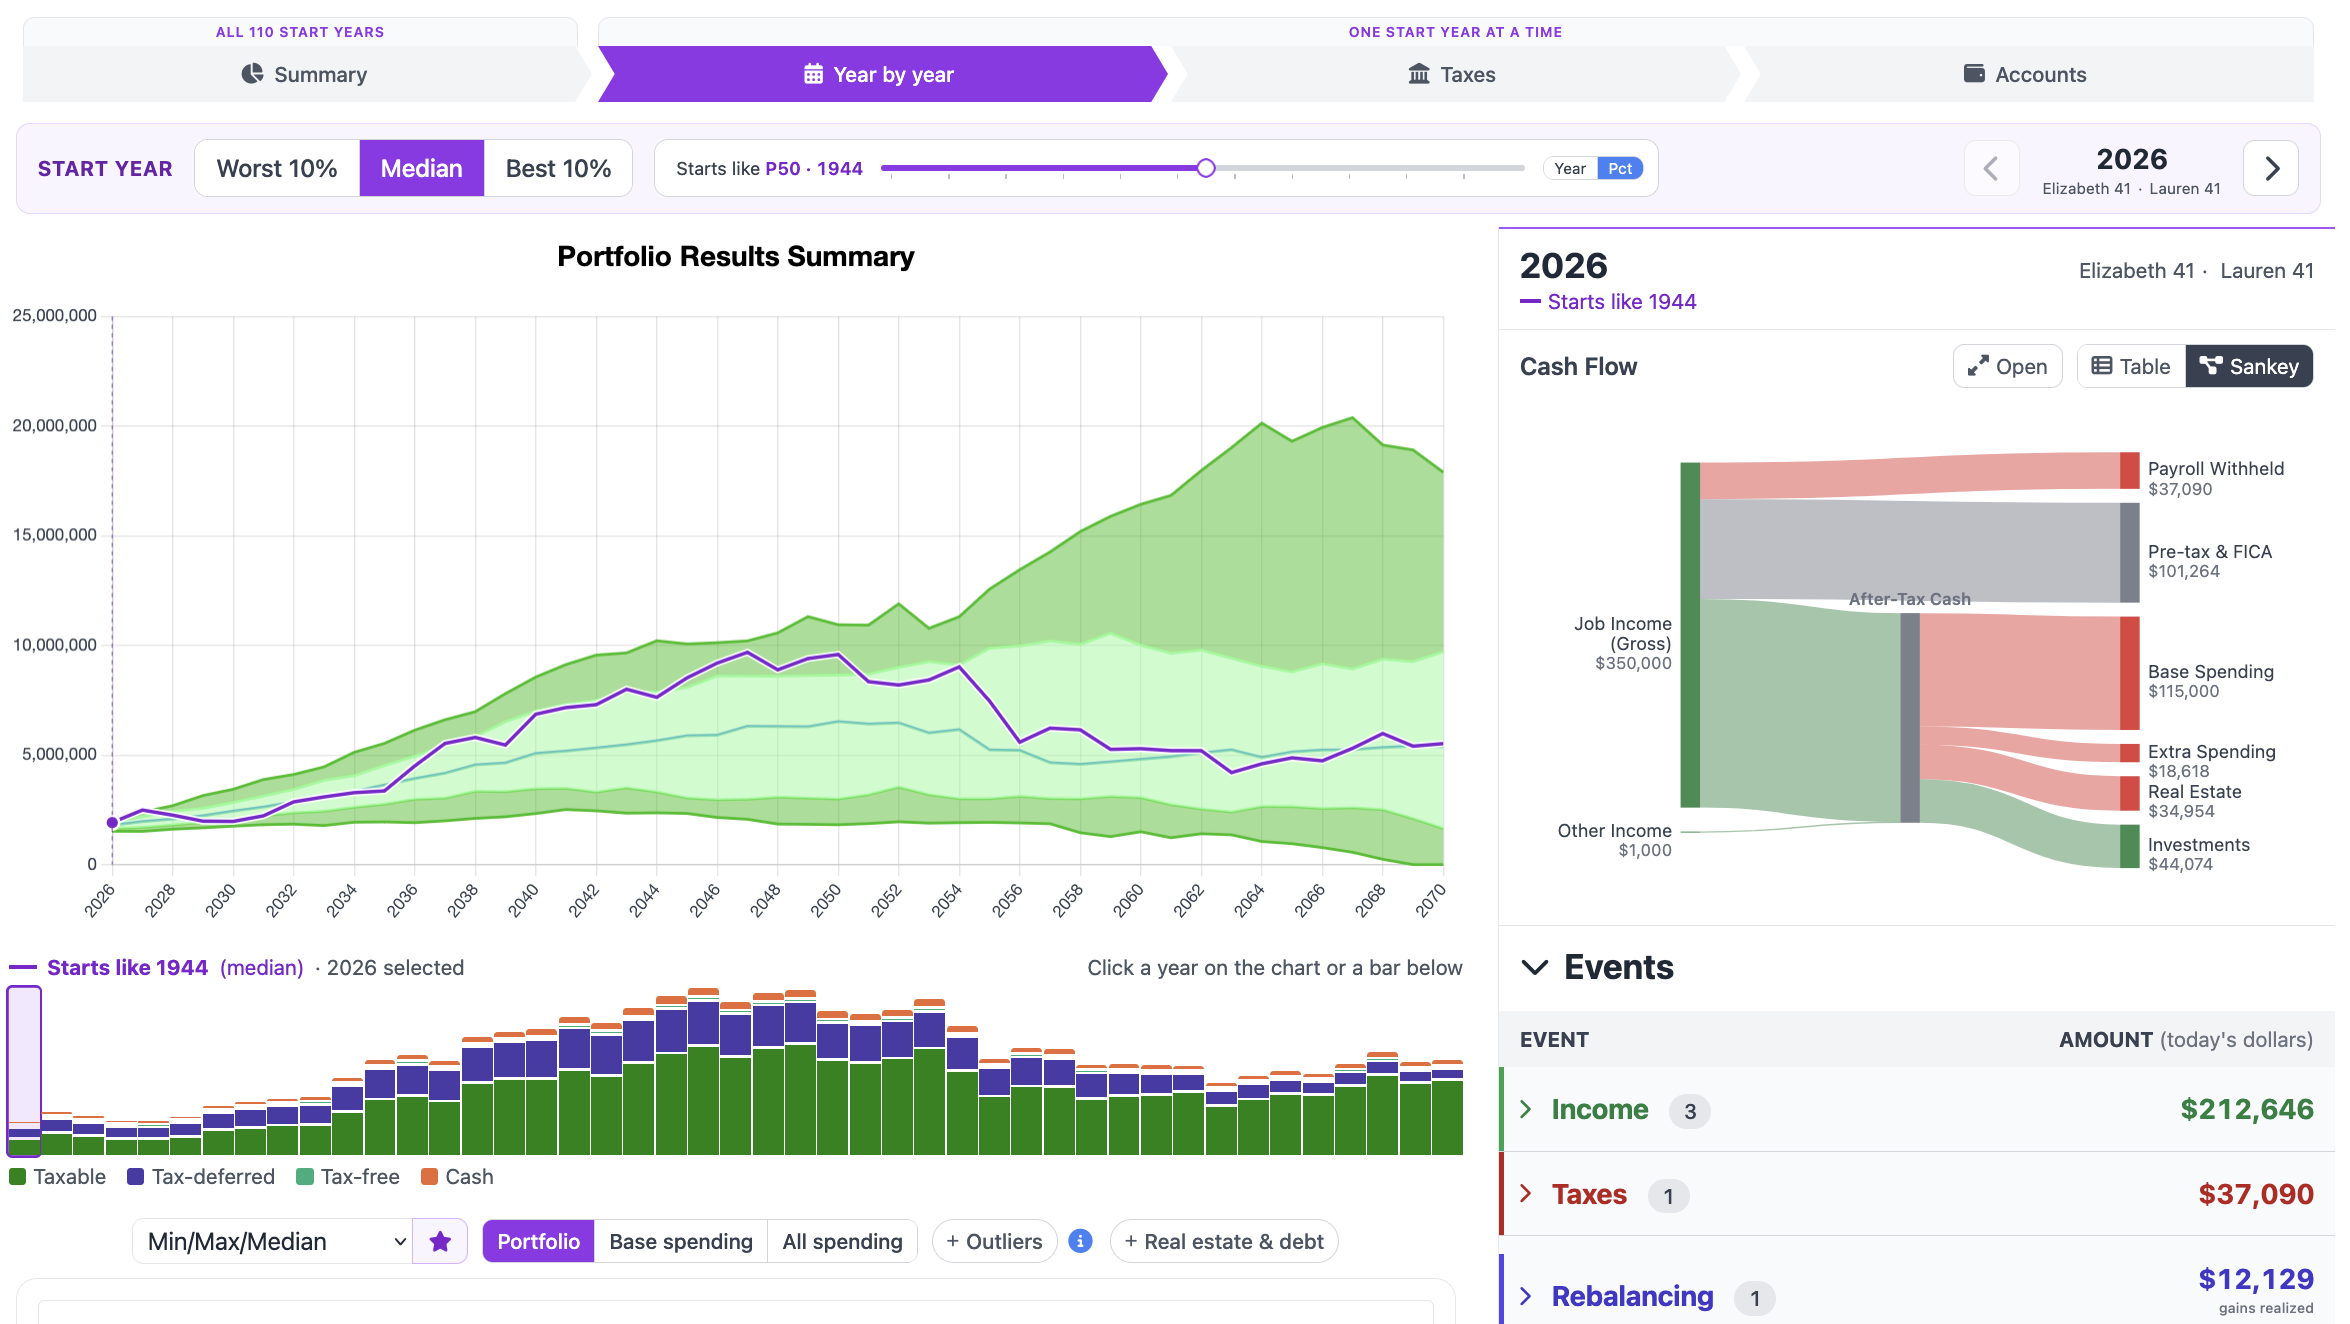
Pick any year of any history and see what happened. The year sits beside the chart, so you can step through a bad history the way you would have lived it.
"One of my favorite simulators is cFIREsim.com"

"The tool that you've built here is absolutely fantastic, really well researched, and tons of great data. Thank you so much for building it."
"We for sure nerded out for hours on cFIREsim for our first WPF Long Weekend retreat."
"If there was a list of heroes of the financial independence movement, I'd advocate for Lauren Boland being on that list... Lauren developed cFIREsim, one of the more powerful and popular retirement calculators among members of the FIRE community."
